Start with the operation
Review delivery types, vehicles, drivers, territory, cargo values and handling practices. Tell us about subcontractors, personal vehicles and any planned changes.
Bring Motive the route requirements before you sign the contract.
A medical courier contract can make a small business look ready to grow overnight. But the insurance exhibit may require coverage that your current auto policy, general liability policy or certificate does not provide.
What you carry matters. A box of disposable supplies, a temperature-sensitive medication and an irreplaceable laboratory specimen create different exposures. A missed delivery window may also create a financial loss that is separate from damage to the shipment itself.
Start with the actual work: who owns the vehicles, who drives them, what travels inside and who is responsible when something goes wrong. Then compare those facts with the contract and policy wording.
A certificate of insurance summarizes coverage; it does not change policy terms or add endorsements. Contract requirements need to be checked against the coverage actually in place.
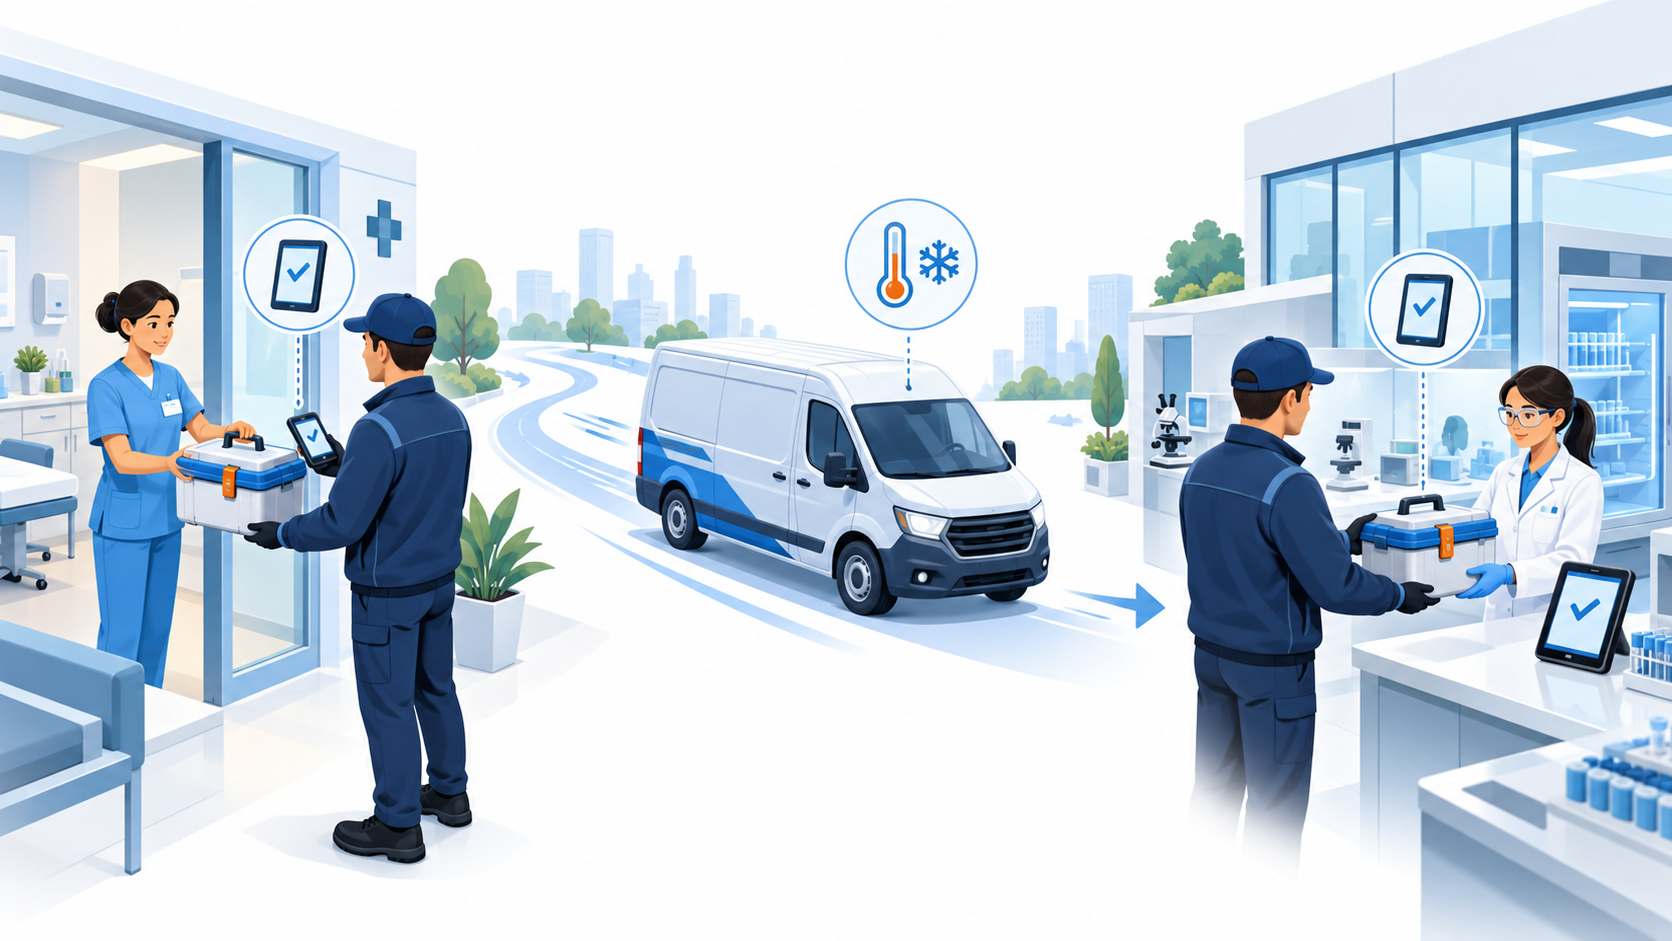
Medical courier businesses should understand the insurance requirements connected to the contracts they are trying to win. Bring the proposed route requirements to Motive so we can help organize the insurance questions before you commit.
Review delivery types, vehicles, drivers, territory, cargo values and handling practices. Tell us about subcontractors, personal vehicles and any planned changes.
Discuss requested limits, coverage types, additional insured wording and other insurance provisions. Identify requirements that need clarification from the client or insurer.
Review available options, relevant exclusions and documentation needs. Coverage placement, endorsements and client acceptance remain subject to review and approval.
Medical courier insurance is usually a combination of policies. The right mix depends on your deliveries, driver model and written agreements. No single coverage automatically protects every vehicle, shipment, service error or privacy event.
Commercial auto liability addresses covered bodily injury and property damage claims arising from business vehicle use. Physical damage coverage may help repair or replace an insured vehicle after a covered loss, subject to deductibles and terms.
Tell the insurer that you perform medical courier work. Vehicle type alone does not describe the exposure, and a personal auto policy may restrict or exclude delivery use. Confirm the vehicles, drivers and operating territory included in the policy.
Contract review: Check the required liability limit, owned-vehicle coverage and any hired or non-owned auto requirements. Explore commercial van insurance.
General liability may respond to covered third-party injury or property damage claims involving your business operations, such as an accident during a pickup at a client location.
It generally does not replace commercial auto liability, professional liability or insurance for goods in your care. Review those exposures separately, including loading and unloading situations where policy wording matters.
Contract review: Compare occurrence and aggregate limits and requested additional insured endorsements. Learn about general liability.
Cargo or an appropriate inland marine policy may address covered loss or damage to property you transport. Standard cargo forms may exclude or limit pharmaceuticals, biological materials, contamination, spoilage or changes in temperature.
Explain the highest value in a vehicle at one time, not only the value of an average delivery. A specimen’s testing or recollection cost may differ from its insurable value. Discuss valuation, theft restrictions, unattended vehicles and refrigeration breakdown explicitly.
Contract review: Confirm covered commodities, valuation, deductibles and any temperature or spoilage endorsements; do not assume “cargo coverage” includes every medical shipment.
A misdelivery, missed deadline or failure to follow a service instruction can lead to a claim for financial loss. Professional liability, also called errors and omissions (E&O), may address certain covered service-related allegations.
Medical courier activities must fit the policy’s description of professional services. Delays, contractual penalties, spoilage and other losses may be excluded or restricted. A contractual promise to reimburse a client is not automatically an insured loss.
Contract review: Discuss the specific services, retroactive date, claims-reporting conditions and exclusions before relying on E&O to satisfy a contract.
Delivery apps, manifests, scanned documents and driver devices may contain sensitive information. Cyber and privacy coverage may provide specified breach response services or liability protection after a covered incident.
Coverage varies for lost paper records, employee mistakes, third-party platforms and electronic data. Explain what information your business receives, stores and accesses, and how drivers use personal devices.
Contract review: Separate the client’s privacy obligations from insurance requirements. Cyber insurance does not establish HIPAA compliance.
If you rent a replacement van or employees use their own cars for deliveries, your business may need hired and non-owned auto liability. These coverages address specified liability exposures involving vehicles your business does not own.
They do not automatically cover damage to those vehicles or replace a driver’s own insurance. Contractor arrangements and vehicle leasing structures need individual review; the coverage does not automatically extend to every subcontractor.
Contract review: Identify who owns, leases and dispatches each vehicle, and whether the contract permits independent contractor drivers.
Workers’ compensation provides benefits for covered work-related employee injuries or illnesses under applicable state law. Lifting, vehicle accidents and repetitive delivery tasks are relevant exposures for courier teams.
Calling a driver an independent contractor does not by itself settle their status under the applicable rules. Review the actual working arrangement, states of operation and any client requirements with appropriate advisers.
Contract review: Discuss workers’ compensation, employers liability limits and any waiver-of-subrogation request. Explore workers’ compensation coverage.
Umbrella or excess liability can add limits above specified underlying liability policies. It may help address a client’s higher limit requirements, depending on the policies and endorsements involved.
Confirm which policies are scheduled underneath it and how exclusions apply. An umbrella does not automatically extend cargo, E&O or cyber coverage, and additional limits do not remove exclusions in the underlying program.
Contract review: Check whether the client accepts an excess structure, the required underlying limits and whether additional insured status extends as requested.
Insurance is one part of route readiness. Your operation also needs procedures suited to the shipments you accept: packaging verification, chain of custody, delivery records, spill response, driver instruction and temperature controls where relevant.
Assign responsibility for each step with the customer. Confirm who classifies and packages shipments, supplies handling instructions, monitors temperature and responds when a package is damaged or a delivery is delayed.
UN3373 identifies Biological substance, Category B. Not every medical specimen falls into this classification. The classification determines the applicable transport requirements; Category A substances and exempt specimens are treated differently.
Category B packaging generally involves a primary receptacle, secondary packaging and rigid outer packaging, with additional leakproof, absorbent and marking requirements as applicable. The correct preparation depends on the material and transport conditions. This overview is not a packaging checklist or a training certification.
Confirm classification and packaging responsibilities with the shipper, and verify the current rules before accepting specimens. Review PHMSA’s infectious-substance guidance.
HHS explains that certain couriers acting only as conduits for protected health information are not business associates. The exception is narrow: access is random or infrequent as needed to perform transport, and any storage is incidental to transmission.
A business that routinely accesses or maintains protected health information may have different obligations. Your use of delivery software, retained records and customer data needs its own review. Being a medical courier does not automatically establish conduit status.
Review the actual services and any business associate agreement with qualified counsel. Read HHS’s courier and conduit explanation.
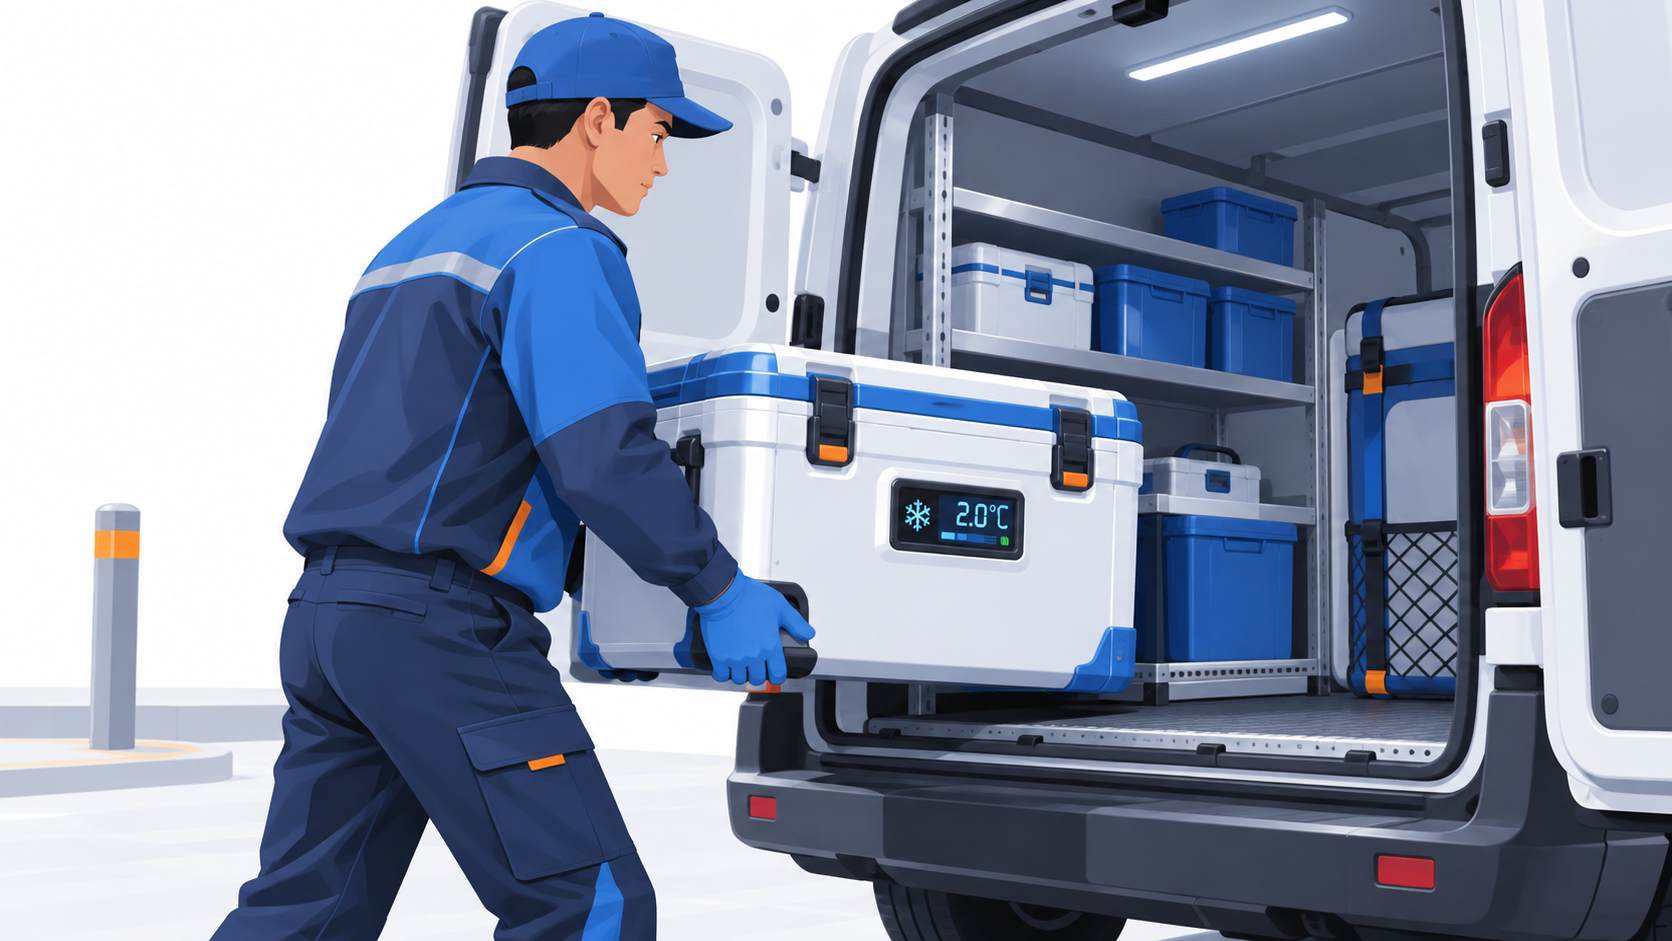
Explain packaging, temperature ranges, monitoring, backup equipment and loss-response procedures to the insurer. Temperature control alone does not mean a spoilage or contamination claim is covered.
Choose the stage that best describes your business for a recommended next step. This is a planning guide, not an insurance approval or compliance certification. Your selection does not submit a review request.
Outline your delivery type, service area, vehicles and driver model. Ask prospective clients for their insurance requirements before committing to a route or vehicle.
Bring Motive the route requirements before you sign the contract. A proposed agreement, insurance exhibit and clear description of the deliveries give us a more useful starting point than a limit alone.
We can help you review the insurance provisions and discuss coverage options. Your client determines whether your documentation meets its requirements; Motive’s review does not guarantee a contract award.
Tell Motive what you transport and how you operate. Coverage availability depends on the business, commodities, underwriting and location.
Independent operators and established businesses moving healthcare deliveries between clinics, hospitals and other facilities.
Couriers carrying laboratory samples with specific pickup windows, handling instructions and documentation requirements.
Dedicated lab routes and multi-driver operations coordinating repeated pickups and time-sensitive deliveries.
Operators transporting medications with cargo values, theft exposures and temperature requirements that need careful review.
Businesses moving supplies and equipment, including high-value items or deliveries that involve additional handling services.
Teams adding vehicles, drivers, subcontractors, service areas or new client agreements.
From Chicago-area healthcare routes to deliveries across Illinois, describe the full territory your business serves. Urban stops, longer trips, overnight parking and cross-state deliveries can all matter to underwriting.
Motive Insurance has locations in Matteson and Wood Dale. We help businesses discuss the insurance side of their operation, including commercial vehicles, liability and employee exposures.
Tell us where vehicles are garaged, where drivers work and whether you cross into Indiana, Wisconsin or other states. Coverage availability and applicable requirements need to be reviewed for the actual operation.
Keep business licensing, motor carrier authority and transport requirements separate from your insurance review; buying a policy does not establish operating authority.
Explore Motive’s commercial insurance coverage →Bring Motive the route requirements before you sign the contract.
Do not include patient names, medical records, driver license numbers or other sensitive records in this form. Discuss document-sharing arrangements directly with Motive.
Call Motive Insurance at 888-943-0888.
Online requests are not connected yet. This form checks your entries locally; it does not send information to Motive.
A medical courier may need commercial auto, general liability, cargo or inland marine, professional liability, cyber/privacy, hired and non-owned auto, workers’ compensation and umbrella coverage. The appropriate mix depends on the vehicles, drivers, shipments and contract requirements.
Personal auto policies may exclude or restrict paid delivery and other business uses. Describe your medical courier work to an agent before accepting deliveries, and confirm coverage for the actual vehicle and activity.
Not automatically. Cargo policies may exclude or limit biological materials, pharmaceuticals, temperature changes, spoilage and contamination. Review the commodities, valuation and endorsements with the insurer before relying on coverage.
Pricing depends on factors such as location, vehicle and driver details, driving history, delivery type, radius, cargo values, limits and prior losses. A review of your operation and contract requirements is needed for a meaningful quote.
HIPAA status and insurance are separate questions. HHS describes a narrow conduit exception for certain transport-only services. Your actual access to, use of and retention of protected health information determines the analysis. Review the arrangement with qualified counsel and discuss privacy coverage separately with your agent.
No. Shipment classification, packaging, marking and handling requirements are operational responsibilities. An insurance policy does not certify compliance or replace appropriate instruction and procedures for transporting specimens.
Yes. Bring the proposed insurance requirements and a description of your routes to Motive. We can discuss coverage options and questions to clarify with the client or insurer. The review does not guarantee policy availability, legal compliance or acceptance by the client.
Yes. Start with your planned delivery type, service area, vehicle and driver model, and any requirements supplied by prospective clients. Coverage options remain subject to underwriting, even when you have not started operating.
A certificate documents certain policy information but does not add coverage or change exclusions. Your contract may require specific endorsements, limits or insured status. Confirm the actual policies and endorsements as well as the client’s documentation requirements.
Bring Motive the route requirements before you sign the contract. Let’s talk through your operation and the coverage the opportunity calls for.